

Over the last six months, Tecnoglass’s shares have sunk to $37.98, producing a disappointing 17.1% loss - a stark contrast to the S&P 500’s 8.9% gain. This might have investors contemplating their next move.
Is there a buying opportunity in Tecnoglass, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Tecnoglass Not Exciting?
Despite the more favorable entry price, we don’t have much confidence in Tecnoglass. Here are three reasons we avoid TGLS, plus one stock we’d rather own.
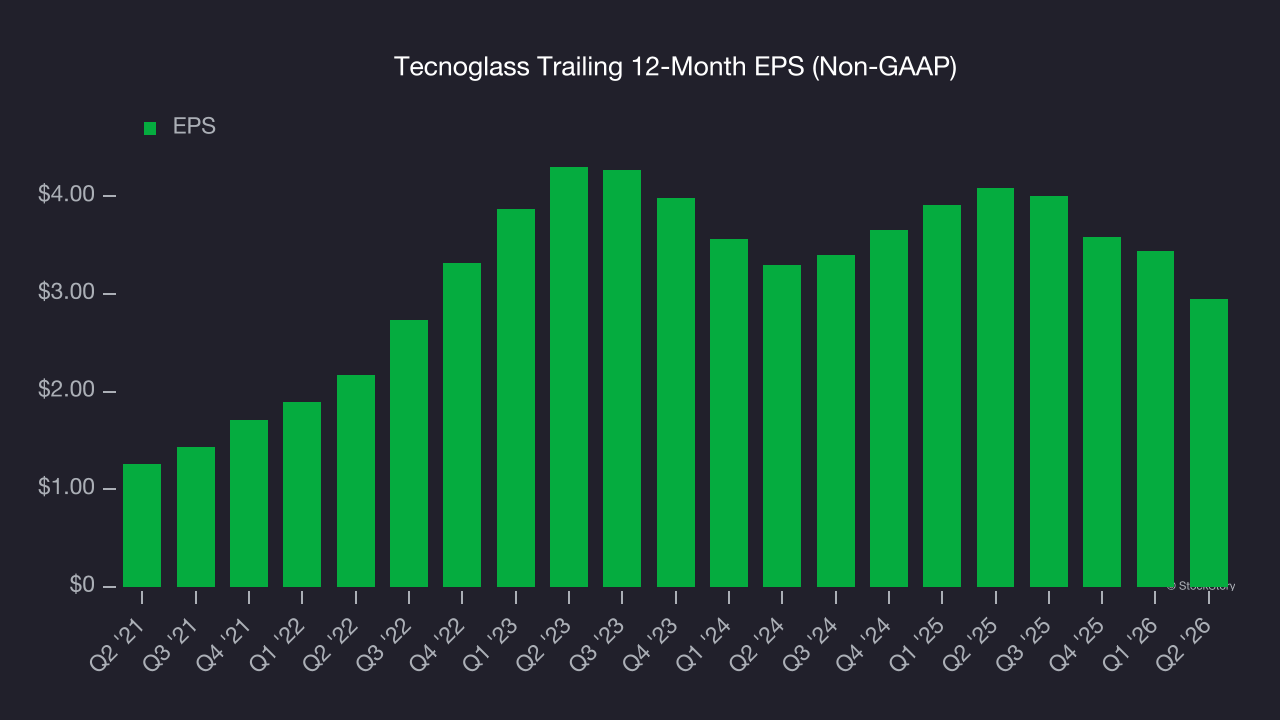
1. EPS Took a Dip Over the Last Two Years
Although long-term earnings trends give us the big picture, we like to analyze EPS over a shorter period to see if we are missing a change in the business.
Sadly for Tecnoglass, its EPS declined by 5.5% annually over the last two years while its revenue grew by 13.3%. This tells us the company became less profitable on a per-share basis as it expanded.
2. Free Cash Flow Margin Dropping
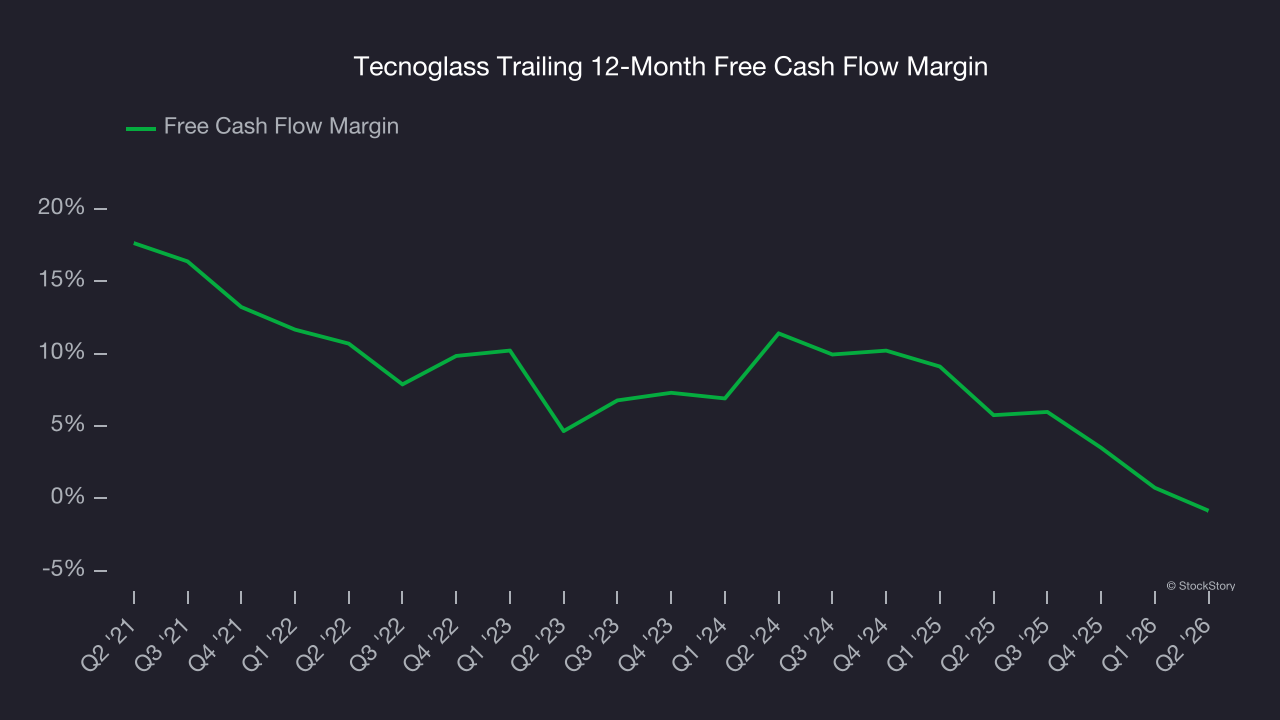
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
As you can see below, Tecnoglass’s margin dropped by 11.5 percentage points over the last five years. This along with its unexciting margin puts the company in a tough spot, and shareholders are likely hoping it can reverse course. If the trend continues, it could signal it’s becoming a more capital-intensive business. Tecnoglass’s free cash flow margin for the trailing 12 months was breakeven.
3. New Investments Fail to Bear Fruit as ROIC Declines
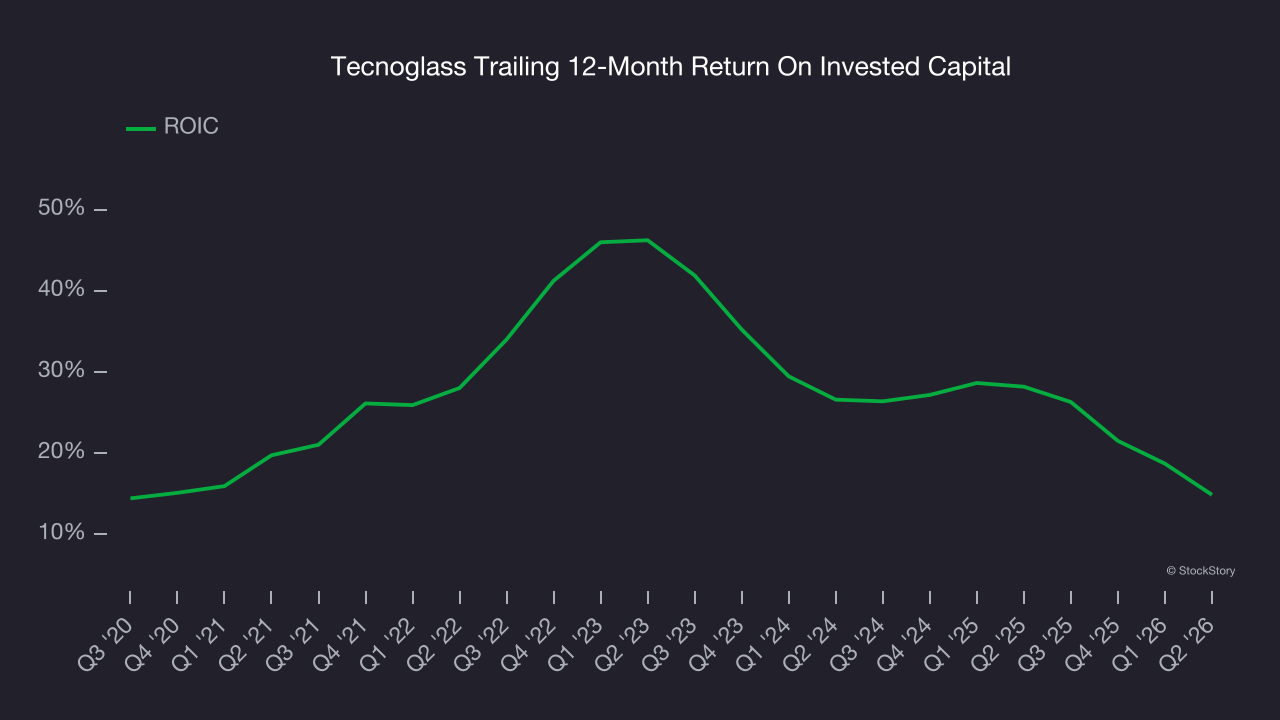
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Unfortunately, Tecnoglass’s ROIC has decreased significantly over the last few years. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
Tecnoglass isn’t a terrible business, but it doesn’t pass our bar. Following the recent decline, the stock trades at 13.4× forward P/E (or $37.98 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re fairly confident there are better investments elsewhere. We’d suggest looking at our favorite semiconductor picks and shovels play.
Stocks We Like More Than Tecnoglass
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.